Help & Guides · 3-Bucket Models · Constant Refilling
How the Constant Refilling Calculators Work
The bucket rules behind all four Constant Refilling calculators, what each calculator solves for, and how the Monte Carlo analysis tests a plan.
1
How the Buckets Work
The Safety Bucket is presumed to hold lower-return, low-risk debt, while the Income Bucket holds higher-risk bonds and other higher-earning fixed income.
Each year, the Safety Bucket pays the retirement expenses. The Income Bucket then refills the Safety Bucket, and the Growth Bucket refills the Income Bucket to bring it back to its target level.
Example: if the Safety Bucket holds 5 years of expenses and the Income Bucket holds 3 years of refills, spending one year of expenses leaves 4 years in the Safety Bucket. The Income Bucket tops the Safety Bucket back up to 5 years, and the Growth Bucket tops the Income Bucket back up to 3 years.
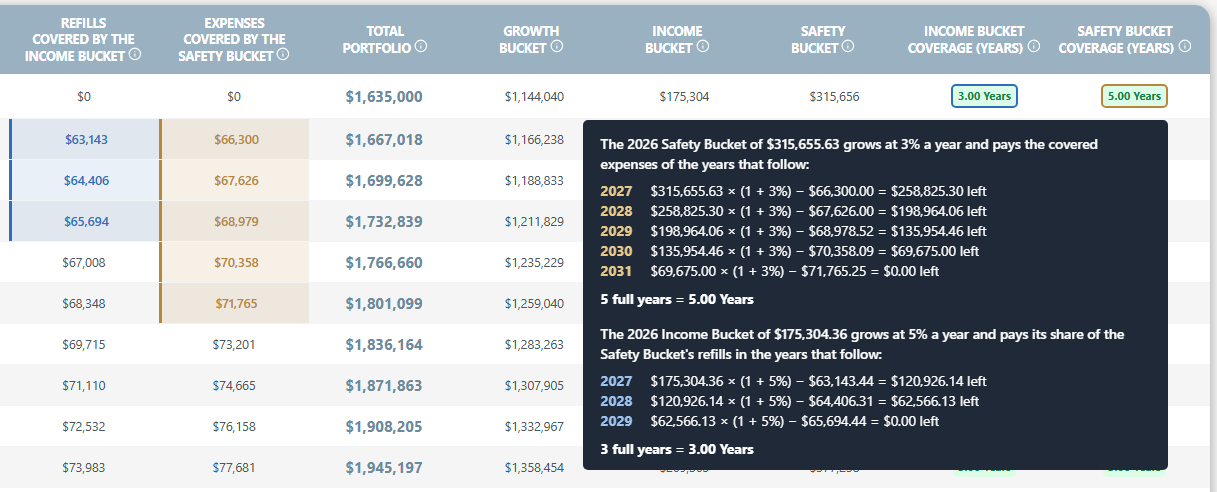
The Safety Bucket, worth $315,656, covers the next 5 years of expenses. The Income Bucket, worth $175,304, covers the next 3 years of the Safety Bucket's refills.
2
Safety Bucket Glidepath
The calculator allows you to introduce a glidepath that changes the Safety Bucket's target level over time.
You can specify:
•
Whether the target number of years of expenses increases or decreases over time.
•
The minimum and maximum number of years of expenses the Safety Bucket can hold.
•
When the target changes and how frequently it changes.
This allows you to model a Safety Bucket that evolves throughout retirement rather than maintaining a constant target.
3
Income Bucket Glidepath
The calculator allows you to introduce a glidepath that changes the Income Bucket's target level over time.
You can specify:
•
Whether the target number of years of Safety Bucket refills increases or decreases over time.
•
The minimum and maximum number of years of Safety Bucket refills the Income Bucket can hold.
•
When the target changes and how frequently it changes.
This allows you to model a Income Bucket that evolves throughout retirement rather than maintaining a constant target.
4
Expense Coverage
You can choose the percentage of essential and discretionary expenses used to calculate the Safety Bucket's target. The permitted range is 100%–200%.
This percentage determines the Safety Bucket's target size, not the expenses it actually pays. The Safety Bucket continues to pay the full actual expenses each year.
For example, choosing 150% coverage allows the Safety Bucket to hold more than the amount required for its preset years of expenses. This provides an additional reserve against unexpected spending shocks.
5
Income Bucket Coverage
You can choose what percentage of the Safety Bucket's refills is used to calculate the Income Bucket's target. The permitted range is 100%–200%, and you can change it partway through the plan.
At 100%, the Income Bucket holds exactly the refills it is sized for. Anything above 100% adds a reserve.
6
Uploading Your Own Expenses
Instead of using the calculator's standard expense inputs, you can upload your own yearly expenses.
This is useful when expenses do not follow the standard growth assumptions or when you need to include irregular expenses and inflows. Inflows can be entered as negative expenses.
7
Planning Beyond the Last Year of Retirement
The calculator offers two options for determining how the Safety Bucket's and Income Bucket's targets are handled toward the end of the plan.
Option 1 · Safety Bucket
Expenses end with retirement
The Safety Bucket only needs to cover expenses through the final year of the plan. As fewer years of expenses remain, its target can decline, allowing the Safety Bucket to wind down toward the end of retirement.
Option 1 · Income Bucket
Expenses end with retirement
The Income Bucket only needs to cover Safety Bucket refills through the final year of the plan. As fewer years of refills remain, its target can decline, allowing the Income Bucket to wind down toward the end of retirement.
Option 2 · Safety Bucket
Maintain the target beyond retirement
The Safety Bucket continues to target the preset number of years of expenses, even in the final years of the plan. This means it may retain funds to cover expenses beyond the chosen planning horizon.
Option 2 · Income Bucket
Maintain the target beyond retirement
The Income Bucket continues to target the preset number of years of Safety Bucket refills, even in the final years of the plan. This means it may retain funds to cover refills beyond the chosen planning horizon.
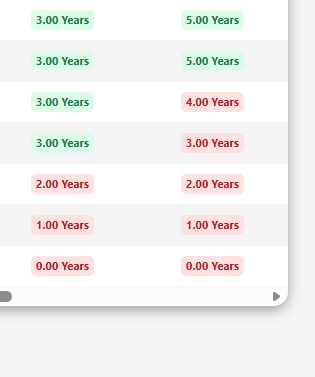
Option 1: in the final years, the Income Bucket (left) and Safety Bucket (right) wind down to 0 years.
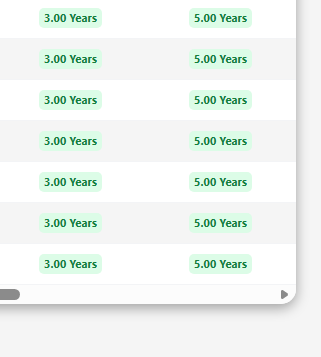
Option 2: the Income Bucket (left) stays at 3 years and the Safety Bucket (right) at 5 years to the last year.
The second option is useful for retirees who want to keep both Buckets at their targets even in the final year of the plan, particularly because the actual end of retirement is uncertain.
8
When the Initial Portfolio Is Insufficient
In some cases, the Growth Bucket may not have enough money to replenish the Income Bucket as required throughout retirement while also meeting the chosen legacy target.
When this happens, the calculator determines a higher initial portfolio value that would meet the model's requirements and achieve the chosen legacy level.
The four Constant Refilling calculators
All four follow the Bucket rules above. Each one solves for a different question.
Final Legacy
The largest legacy you can leave, given your starting corpus and expenses.
Retirement Corpus Required
The smallest starting corpus that covers your expenses and reaches your legacy goal.
Maximum Discretionary Spending
The most you can spend on discretionary expenses while still meeting your goals.
Maximum Income Bucket Levels Allowed Under Bucket Approach
The most years of Safety Bucket refills the Income Bucket can hold while still meeting your goals.
Monte Carlo Analysis
The Monte Carlo feature runs multiple simulations using varying investment returns to evaluate how often a retirement plan meets its goals.
1
Defining Success
You can specify the minimum legacy required for a simulation to be considered successful. A simulation counts as a success if the portfolio never runs out during the plan and ends with at least this legacy.
2
Growth Bucket Returns
You can specify an average annual return and a standard deviation for the Growth Bucket's returns.
The average return sets the expected return assumption, while the standard deviation determines the volatility of returns across simulated years.
3
Safety Bucket and Income Bucket Returns
You can choose to randomize the Safety Bucket's and Income Bucket's annual returns, each on its own, allowing their returns to vary from year to year rather than remain fixed.
4
Skipping Income Bucket Refills
You can set a threshold for refills from the Growth Bucket based on its compounded return over the previous three years. If that 3-year return falls below the chosen threshold, the Growth Bucket does not refill the Income Bucket that year. Such a year is called a skip year.
Example: if the threshold is −5%, the refill is skipped when the Growth Bucket's compounded return over the previous three years is below −5%.
If fewer than three years have passed since the start of the plan, the refill decision is based on the available Growth Bucket returns since the plan began.
In a skip year, the Income Bucket continues to refill the Safety Bucket normally. If both the Safety Bucket and the Income Bucket run out, the Growth Bucket pays the unpaid portion of expenses.
5
Planning Beyond the Last Year of Retirement
Monte Carlo analysis always maintains the Safety Bucket and Income Bucket at their target levels through the end of the plan, corresponding to Option 2 above. This applies regardless of which option was selected on the main calculator.
6
Number of Simulations
You can choose how many simulations to run, up to a maximum of 10,000. Running more simulations provides a broader sample of possible outcomes, although it does not guarantee that the results will predict actual future performance.
Ready to try it?
Pick one of the four Constant Refilling calculators and run your own numbers.
Go to Calculators
Product
Calculators
Pricing
Contact Us
Resources
FAQs
Blogs
Help & Guides
• 2-Bucket Model
• 3-Bucket Models
◦ Constant Refilling Model
◦ Stacked Model
◦ Core & Lifestyle Model
Follow Us
© 2026 Cherish Retirement LLC. All rights reserved.
Privacy Policy
•
Terms of Service
Disclaimer:
The content and tools on this website are provided for informational and educational purposes only and do not constitute financial, investment, tax, or legal advice.
All calculations, projections, and outputs are provided for illustrative purposes only. We make no representations or warranties as to their accuracy and assume no responsibility for errors, omissions, or outcomes resulting from their use.
These tools are not a comprehensive financial plan and should not be relied upon as the sole basis for making financial decisions. Actual results may vary due to market conditions, inflation, taxes, spending behavior, and other factors.
Users are encouraged to consult a qualified financial professional, preferably acting in a fiduciary capacity, before making any significant financial or retirement-related decisions. All content and tools are provided “as is,” without warranties of any kind.